Since 2026, the global AI computing power revolution has exploded in full swing. The rapid expansion of fields such as ChatGPT, large model training, and high-end AI servers has unexpectedly ignited the market demand for MLCCs (Multi-Layer Ceramic Capacitors). In particular, high-end and high-capacity MLCCs are in an extremely tight supply situation of "hard to find", with prices continuing to rise. Manufacturers at home and abroad have successively expanded production to cope with this, and the entire passive component industry has ushered in a new growth cycle. This phenomenon is not a short-term supply-demand disturbance, but the result of the resonance of three factors: structural explosion on the demand side, rigid increase on the cost side, and contraction on the supply side, which has profoundly affected the pattern of the global electronic component industry chain.
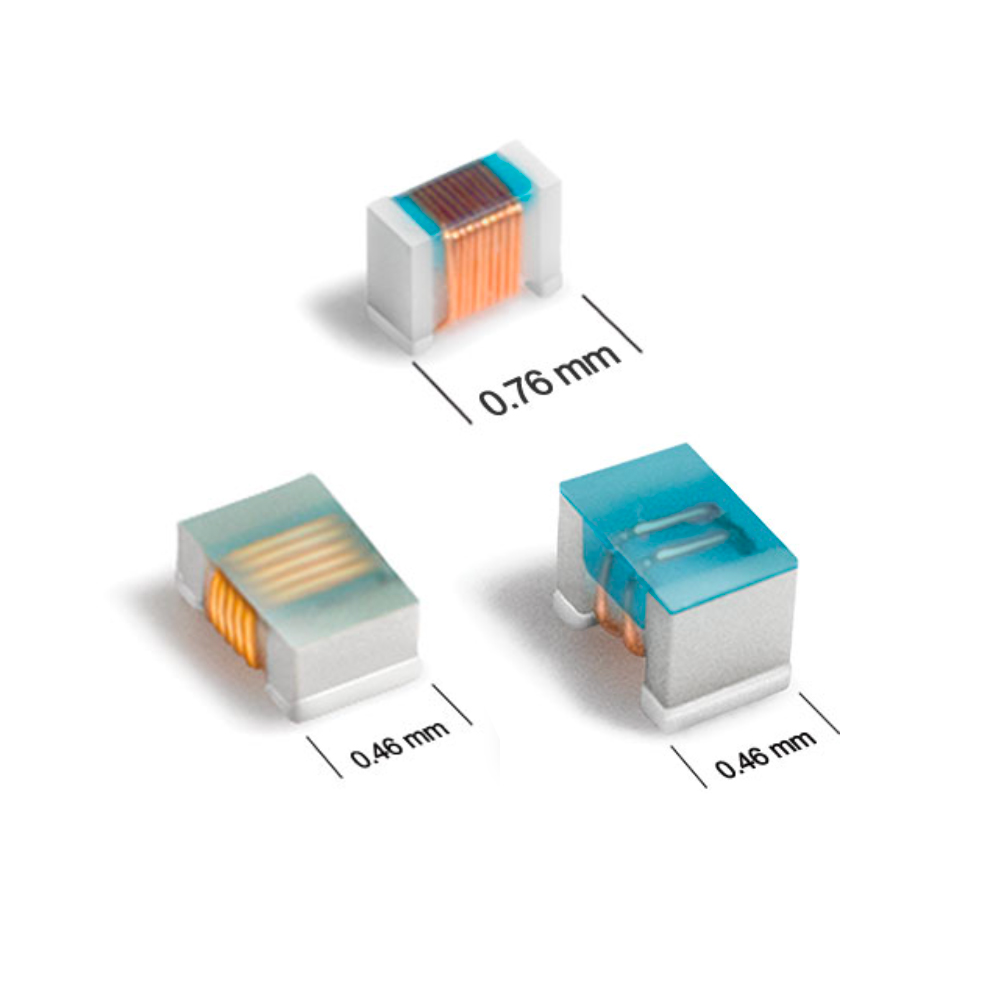
As an indispensable passive component in electronic equipment, MLCCs have core functions of filtering power supply noise, smoothing voltage fluctuations, and compensating for instantaneous current, known as the "grain of electronic components". They are widely used in consumer electronics, automotive electronics, industrial control and other fields. The explosion of AI computing power has led to an exponential growth in the demand for MLCCs, and the core reason lies in the harsh requirements of high-end AI servers for power supply stability — AI servers are equipped with a large number of high-performance GPUs, with a single-unit power consumption of up to 10,000W, which is more than 5 times that of ordinary servers. When GPUs operate, the current jumps from dozens of amperes to hundreds of amperes in an instant. Such drastic fluctuations must be smoothed by a large number of MLCCs, otherwise, it will lead to chip damage and operation interruption.
The huge gap in usage has become the core driver for AI computing power to ignite MLCC demand. Data shows that the MLCC usage of traditional ordinary servers is only 2,000-4,000 units, while the usage of AI servers has grown geometrically: Nvidia A100 8-card AI servers require about 48,000 MLCCs, GB200 architecture (36 cards) usage jumps to 236,000 units, and the latest GB300 platform (72 cards) has a single-unit usage as high as 443,000 units. The MLCC consumption of a single AI cabinet can even reach 440,000 units, which is more than 110 times that of ordinary servers. Murata of Japan estimates that the annual average growth rate of MLCC demand for AI servers will reach 30%, and by 2030, the relevant demand will increase by 3.3 times compared with 2025, indicating the sustainability of the demand explosion.
The explosive growth in demand has directly led to an imbalance between supply and demand in the high-end MLCC market, and "hard to find" has become the industry norm. At present, the utilization rate of high-end production lines of global leading MLCC enterprises has exceeded 90%-95%, and the order volume of some enterprises has reached twice the production capacity. Customers need to wait for several months to receive goods after placing orders, and even the phenomenon of "price gouging to grab goods" has appeared. At the same time, the price of high-end MLCCs has continued to rise. Since 2026, the spot price of high-capacity and automotive-grade MLCCs has increased by more than 20%. Global giants such as Murata and Samsung are brewing price increases, and domestic manufacturers have followed suit, further intensifying the tense atmosphere of the market.
In addition to the explosion on the demand side, the rigid increase on the cost side and the contraction on the supply side have further amplified the supply-demand contradiction. In the production cost of MLCCs, raw materials account for 30%-65%, among which silver accounts for 42%-58% of the electrode cost. Since 2025, the prices of global metal raw materials such as silver, copper and nickel have risen sharply, among which the price of silver has increased by more than 143%, and the spot price of London silver has exceeded 76 US dollars per ounce, directly pushing up the production cost of MLCCs. In addition, the core raw materials of high-end MLCCs — ceramic powder, nano-nickel powder, etc. — have long been monopolized by Japanese enterprises. The improvement of environmental protection requirements has further intensified the supply shortage. Coupled with the supply chain fluctuations caused by geopolitical factors, the supply side is difficult to quickly respond to the demand growth.
The tight supply-demand pattern has also brought historic opportunities for domestic MLCC manufacturers, and the process of domestic substitution has accelerated in an all-round way. For a long time, the global MLCC market has been monopolized by Japanese enterprises such as Murata and TDK, accounting for more than 70% of the market share, while domestic manufacturers mainly focus on the mid-to-low-end fields. Now, with the explosion of AI demand, domestic leading enterprises have accelerated technological breakthroughs and gradually entered the high-end market: Fenghua Hi-Tech has passed the full-series certification of Nvidia, and has批量 supplied HBM-matched high-frequency MLCCs to ODM factories such as Foxconn. The AI orders in the first quarter of 2026 increased by 120% year-on-year, and it plans to add 15.1 billion high-end MLCCs of monthly production capacity; Sanhuan Group has realized the independent R&D and production of upstream materials such as ceramic powder, mass-produced high-capacity MLCCs with a dielectric layer thickness of 1 micron, and its market share of MLCCs for 5G base stations exceeds 40%; upstream enterprises such as Guoci Materials and Boqian New Materials have broken the monopoly of Japanese enterprises in the fields of ceramic powder and nano-nickel powder respectively, providing support for the high-endization of domestic MLCCs.
From the perspective of industry trends, the continuous upgrading of AI computing power will drive the long-term growth of MLCC demand, and high-endization and localization have become the core directions. With the continuous development of fields such as AI large models, edge computing, and Industry 5.0, the requirements for the capacity, precision and stability of MLCCs will be further improved, and the demand for high-capacity, ultra-miniature and high-temperature resistant high-end MLCCs will continue to rise. At the same time, supported by policies, the second phase of the National Integrated Circuit Industry Investment Fund has invested more than 2 billion yuan to support the development of the basic electronic component industry, aiming to achieve a localization rate of more than 60% for high-end materials by 2027. The domestic MLCC industrial chain is accelerating the "triple leap" of scale, localization and high-endization.
In general, the explosion of AI computing power has not only reshaped the supply-demand pattern of the MLCC market, but also promoted the upgrading and transformation of the entire passive component industry. At present, the situation of "hard to find" high-end MLCCs is difficult to ease in the short term. It is expected that in the next 1-2 years, the industry will continue to be in an upcycle of volume and price growth. With technological breakthroughs and supply chain advantages, domestic manufacturers are expected to occupy a larger share in the global high-end MLCC market and achieve a leap from "following" to "leading".